Ontario HST Rebate on a $1 Million Home
Real Estate, Ontario HST Rebates
Ontario HST Rebate on a $1 Million Home
Buying a brand-new home in Ontario is expensive enough without a surprise six-figure tax bill. The good news: for a limited time, Ontario’s enhanced HST programs can turn that tax hit into a major refund opportunity—especially on a $1 million home and for first-time buyers.
The HST Hit on a $1 Million New Home in Ontario
Start with the basic math. On a $1,000,000 new home in Ontario, HST at 13% adds a staggering $130,000 to the price. That tax breaks down as follows:
5% federal portion of HST on $1,000,000, and
8% Ontario provincial portion of HST on $1,000,000.
Why the Legacy Rebates Pay $0 at $1 Million
Before Ontario’s enhanced measures, buyers relied on legacy new housing rebates. At $1 million, those programs effectively shut off:
The legacy federal rebate on new homes was capped at a maximum of about $6,300, and it phased out well below $1 million. By the time you reached a $1 million price, the federal legacy rebate was reduced to $0.
The legacy Ontario rebate on the provincial portion also offered $0 at a $1 million value. There was no provincial relief left at that price point.
Under the old rules, a buyer of a $1 million new home in Ontario could pay the full $130,000 in HST and receive no rebate at all.
Ontario’s Enhanced Program: Turning $130,000 of HST into Up to $130,000 Back
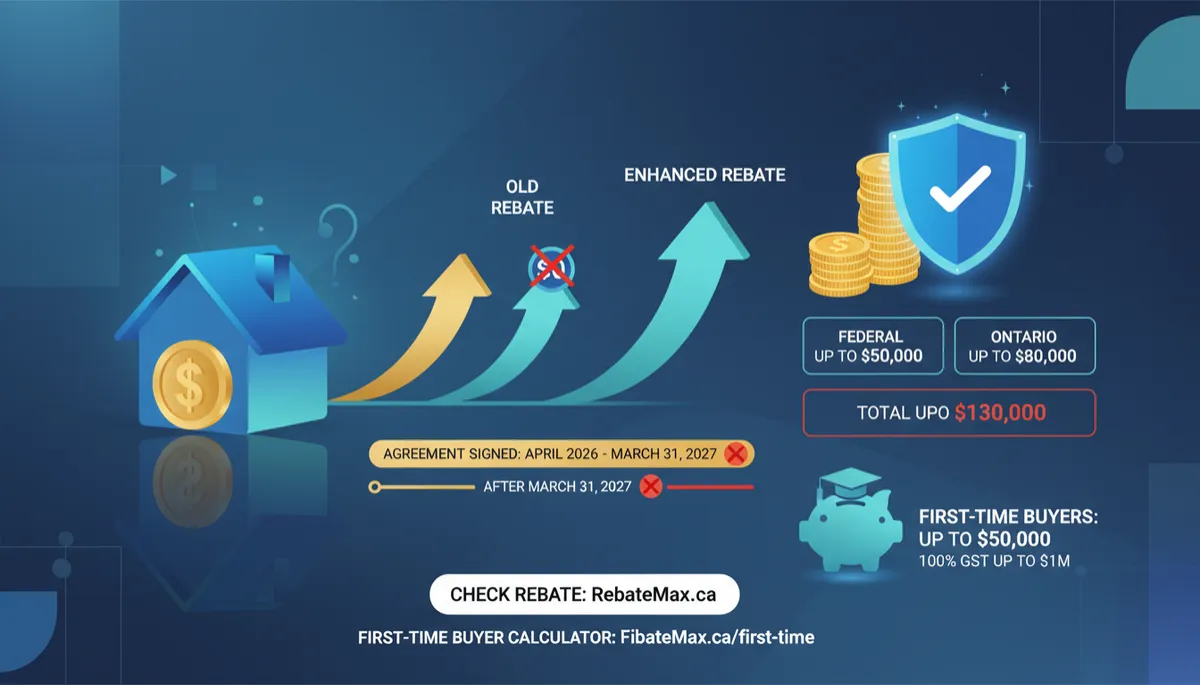
Under the enhanced HST relief available only in Ontario, and only for agreements signed between April 1, 2026 and March 31, 2027, the same $1 million new home can unlock up to $130,000 back.
It is essential to break this into two separate pieces:
Federal part – up to $50,000: Under the enhanced framework, the federal side can refund up to $50,000, corresponding to 100% of the 5% federal portion on a $1 million home.
Ontario’s enhanced rebate – up to $80,000: Ontario’s own enhanced program can return up to $80,000, which lines up with the 8% provincial portion on that $1 million price.
Together, for a qualifying Ontario purchase in that window, those two parts can add up to as much as $130,000 back on a $1 million new home. This full amount is not available outside Ontario; it is a province-specific combination of federal and Ontario relief tied to Ontario’s enhanced program rules.
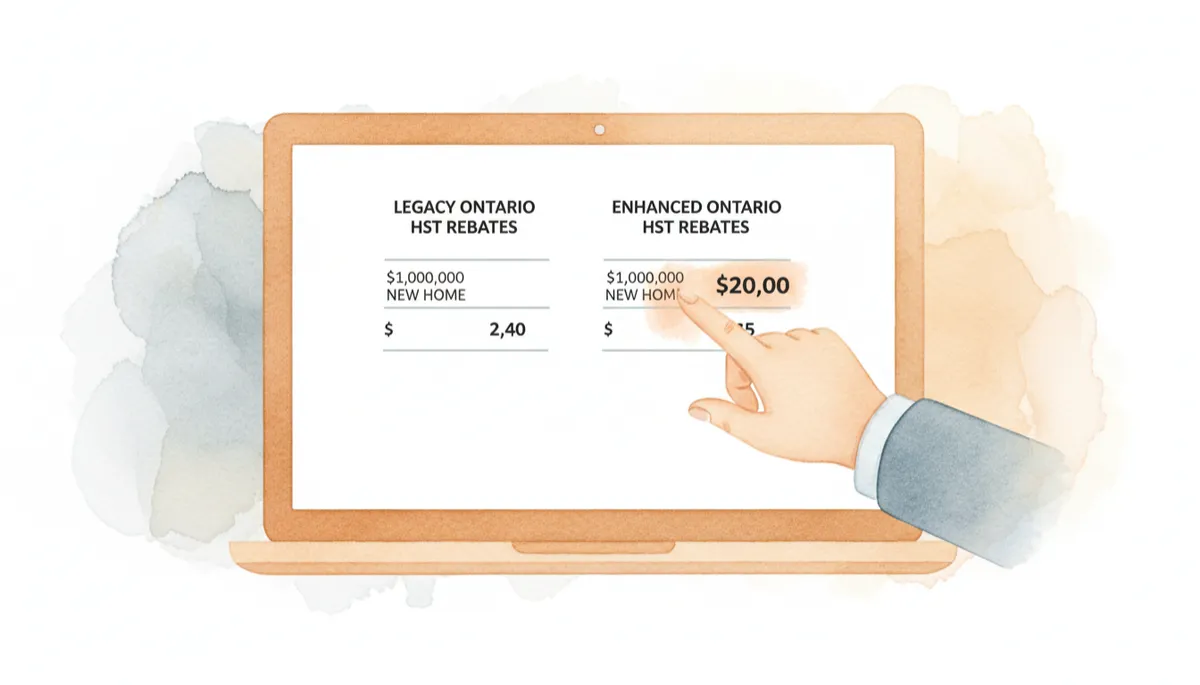
Comparing legacy and enhanced rules shows how Ontario’s window can unlock up to $130,000.
Why $1 Million Is the Sweet Spot for First-Time Buyers
If you are a first-time buyer, the $1 million mark is more than just a round number—it can be a strategic target. The federal First-Time Home Buyer GST Rebate is designed to be most generous right up to that price point.
For qualifying first-time buyers, the program can return 100% of the GST (federal portion) on a new home priced up to $1 million, which means up to $50,000 back on the federal side. The key detail is that this first-time buyer rebate only starts to phase out above $1 million. Once your purchase price crosses that line, the federal first-time buyer benefit begins to shrink and eventually disappears at higher prices.
Combine that first-time buyer advantage with Ontario’s enhanced provincial relief, and a first-time buyer purchasing a $1 million new home in Ontario—within the right agreement dates—can potentially access the maximum blend of federal and provincial rebates, subject to eligibility and approval.
The Date That Makes or Breaks Your Enhanced Rebate
One of the most misunderstood parts of Ontario’s enhanced HST relief is which date actually matters. It is not when you get your keys, and it is not when the home is finished. The enhanced outcome turns on the agreement signing date.
To be considered under the enhanced Ontario program, the agreement of purchase and sale must be signed between April 1, 2026 and March 31, 2027. If you sign the agreement one day after March 31, 2027, you lose access to those enhanced amounts and fall back on whatever rules apply after the window closes. That difference in timing could be worth up to $130,000 on a $1 million Ontario home.
💡 Practical tip: If your builder expects to release a new phase around that deadline, talk early about when agreements will actually be signed so you understand whether you fall inside or outside the enhanced period.
How RebateMax Helps You Navigate the Fine Print
The combination of legacy rules, enhanced Ontario relief, and first-time buyer programs can be confusing—especially when every detail, from purchase price to signing date, can change your outcome. That is where a dedicated HST rebate filing service like RebateMax can help you understand what you may be entitled to and handle the filing process for you.
While no service can guarantee approval or specific amounts, a specialist can help you:
Confirm whether your agreement date falls within the enhanced Ontario window.
Separate the federal portion (up to $50,000) from Ontario’s enhanced rebate (up to $80,000) on a $1 million home.
Check if you qualify as a first-time buyer and how that status affects your potential refund.
Check Your Rebate Potential Before You Sign
If you are considering a new $1 million home in Ontario—or you have already signed within the April 2026 to March 2027 window—it is worth taking a few minutes to estimate what you could receive back. You can check your rebate potential at rebatemax.ca, and if you are a first-time buyer, you can also use the dedicated free check and calculator at https://rebatemax.ca/first-time-home-buyer-rebate to see how the numbers might work for you, including the possibility of up to $50,000 on the federal side and up to $80,000 from Ontario’s enhanced program on a $1 million home, subject to eligibility.
And if your budget stretches beyond $1 million, keep in mind that at around $1.5 million the math changes again, with different phase-outs and limits that are worth reviewing carefully before you commit.